


September 16, 2026

September 18, 2025
September 10, 2025
July 3, 2025
What Is a Systematic Withdrawal Plan (SWP) and How Does It Work?
Author
Shoonya Team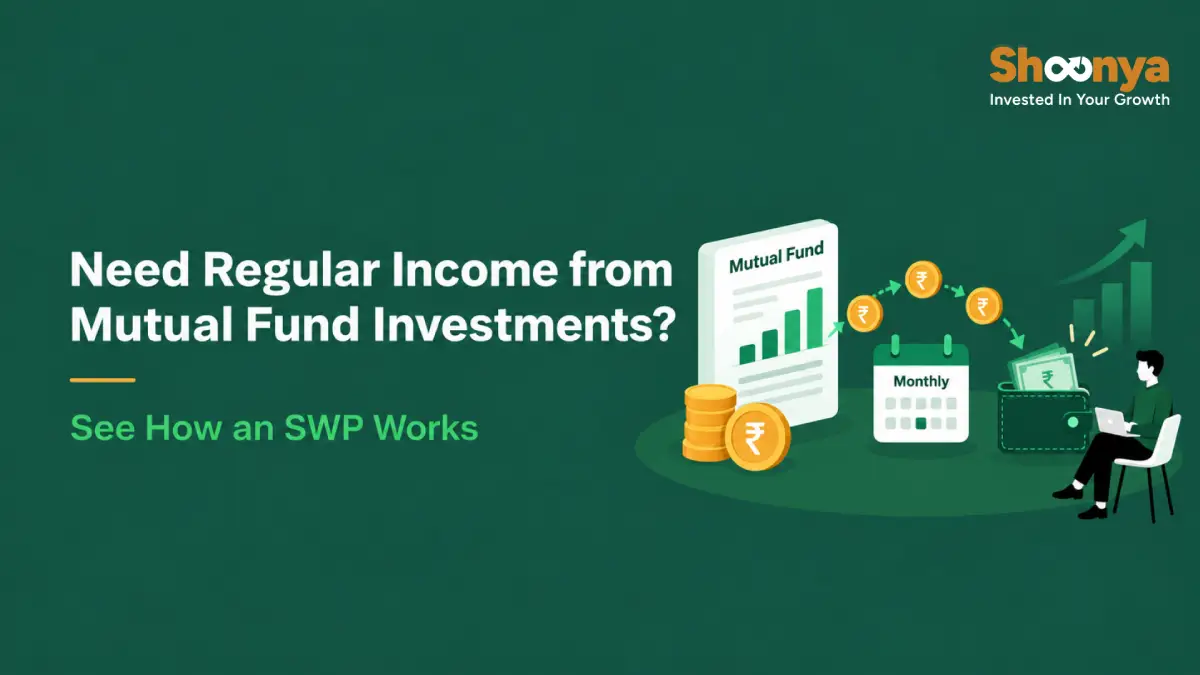
You may spend years building your mutual fund investments. But when you need money from them, withdrawing the entire amount at once may not always be necessary.
A Systematic Withdrawal Plan (SWP) provides another way to access your investment. It lets you withdraw a specified amount at regular intervals while the remaining mutual fund units stay invested.
What Is a Systematic Withdrawal Plan?
A Systematic Withdrawal Plan is a facility that allows you to withdraw a specified amount from a mutual fund scheme at regular intervals. Each withdrawal is processed by redeeming the required number of mutual fund units at the applicable NAV.
The SWP full form is Systematic Withdrawal Plan.
Depending on the mutual fund scheme, you may be able to choose:
- The amount you want to withdraw.
- The frequency of withdrawals.
- The date on which withdrawals are made.
- The period for which you want the SWP to continue.
How Does SWP Work?
An SWP works by automatically redeeming mutual fund units at predetermined intervals to provide the amount you have selected. The number of units redeemed depends on the applicable NAV when each withdrawal is processed.
For example, suppose you have ₹5 lakh invested in a mutual fund and set an SWP of ₹10,000 per month.
- Your SWP date arrives.
- The AMC processes a redemption of ₹10,000.
- The required number of units is calculated using the applicable NAV.
- Those units are deducted from your mutual fund holding.
- The redemption proceeds are paid to your registered bank account.
- Your remaining units continue to stay invested.
For example, if the applicable NAV is ₹50, withdrawing ₹10,000 would require redemption of 200 units.
What Are the Benefits of an SWP?
An SWP provides a structured way to withdraw money from an existing mutual fund investment instead of redeeming the entire investment at once. It can be useful when you need periodic cash flows from your accumulated corpus.
- Regular withdrawals: Receive a specified amount at predetermined intervals.
- Flexibility: Choose the withdrawal amount and frequency from the options offered by the scheme.
- Remaining investment: Units that are not redeemed continue to remain invested.
- Automated process: A standing instruction can automate periodic redemptions.
- Cash-flow planning: Regular withdrawals can help meet recurring financial requirements.
- Customisation: Some schemes offer different withdrawal frequencies and dates.
SEBI’s current framework recognises SWP as a standing instruction for periodic redemption of a specified number of mutual fund units or amount. (Securities and Exchange Board of India)
Who Can Consider an SWP?
An SWP may be considered by mutual fund investors who have accumulated a corpus and want to withdraw from it periodically. Its suitability depends on factors such as financial needs, investment horizon, fund performance and withdrawal amount.
It may be useful for:
- Retirees looking for periodic withdrawals from accumulated investments.
- Investors who need money for recurring expenses.
- Investors who do not want to redeem their entire mutual fund holding at once.
- People looking to create scheduled withdrawals for planned expenses.
An SWP should not be treated as a guaranteed income product because withdrawals come from the redemption of your mutual fund units.
How to Invest in SWP?
You do not invest in an SWP as a separate investment product; you set up an SWP on an eligible mutual fund investment. You need to hold units in a scheme that provides the Systematic Withdrawal Plan facility.
The general process is:
- Select your existing eligible mutual fund investment.
- Check whether the scheme offers an SWP facility.
- Choose your withdrawal amount.
- Select the available withdrawal frequency.
- Choose the start date and duration, where applicable.
- Submit the SWP instruction through the AMC, RTA or supported platform.
- Withdrawals begin according to the registered schedule.
Minimum withdrawal amounts, available dates, frequencies and registration requirements can vary between schemes. For example, one current scheme document allows monthly or quarterly SWPs with a minimum ₹500 instalment, but this should not be treated as a universal SWP minimum. (AMFI)
What Is the SWP Interest Rate?
There is no fixed SWP interest rate because an SWP does not pay interest. Your money remains invested in the underlying mutual fund, whose returns depend on the scheme’s portfolio and market performance.
The amount you receive through an SWP comes from redeeming your mutual fund units, not from a fixed interest payment.
For example:
| Factor | SWP |
|---|---|
| Fixed interest rate | No |
| Source of withdrawal | Redemption of mutual fund units |
| Returns | Depend on underlying mutual fund |
| Guaranteed returns | No |
| Units after withdrawal | Reduce with each redemption |
This distinction is important when comparing an SWP plan with fixed-income products that may offer a predetermined interest rate.
Is SWP Taxable?
Yes, SWP withdrawals can have tax implications because every instalment involves redemption of mutual fund units. Tax is generally calculated on the capital gain arising from the units redeemed rather than treating the entire withdrawal as investment income.
The applicable tax treatment depends on factors such as:
- Type of mutual fund.
- Purchase date of the redeemed units.
- Holding period.
- Cost of acquisition.
- Capital gain generated on redemption.
- Tax rules applicable at the time of withdrawal.
Because an SWP involves repeated redemptions, different instalments can have different capital gains depending on the units being redeemed.
SIP vs SWP: What Is the Difference?
A SIP is used to invest money regularly in a mutual fund, whereas an SWP is used to withdraw money regularly from an existing mutual fund investment.
| Basis | SIP | SWP |
|---|---|---|
| Full form | Systematic Investment Plan | Systematic Withdrawal Plan |
| Purpose | Invest regularly | Withdraw regularly |
| Money movement | Into mutual fund | Out of mutual fund |
| How it works | Purchases units periodically | Redeems units periodically |
| Effect on units | Units are added | Units are reduced |
| Common use | Building an investment corpus | Drawing from an accumulated corpus |
| Returns | Depend on underlying scheme | Remaining investment continues to be market-linked |
How Can an SWP Calculator Help?
An SWP calculator estimates how regular withdrawals may affect your mutual fund corpus over a chosen period. It can show how long an investment may potentially last based on assumed returns and withdrawal amounts.
Typically, an SWP calculator asks for:
- Initial investment amount.
- Expected rate of return.
- Withdrawal amount.
- Withdrawal frequency.
- Investment or withdrawal period.
The results are only estimates. Actual mutual fund returns and NAV movements can be different from the assumed rate used in the calculation.
What Should You Consider Before Starting an SWP?
Before starting an SWP, consider whether your withdrawal amount is sustainable relative to your investment corpus and financial requirements. Frequent or high withdrawals can reduce the number of units you hold and may eventually deplete your investment.
Consider:
- Withdrawal amount: Decide how much you actually need periodically.
- Withdrawal frequency: Choose a schedule suited to your cash-flow requirements.
- Fund performance: Mutual fund returns are market-linked and can fluctuate.
- Corpus size: Higher withdrawals can reduce your investment faster.
- Taxation: Each SWP instalment is a redemption and may result in capital gains.
- Exit load: Check whether the scheme applies an exit load to the units being redeemed.
- Investment horizon: Consider how long you need the withdrawals to continue.
Can an SWP Exhaust Your Mutual Fund Investment?
Yes, an SWP can eventually exhaust your mutual fund corpus if withdrawals continue to reduce the available units. This can happen faster when withdrawal amounts are high or investment returns are insufficient to offset the redemptions.
SWP withdrawals should therefore be planned based on your corpus, expected requirements and investment horizon rather than assuming that the original investment will remain unchanged.
Conclusion
A Systematic Withdrawal Plan provides a structured way to withdraw money periodically from an existing mutual fund investment. Instead of redeeming the entire investment at once, an SWP automatically redeems the required units according to your chosen schedule.
However, an SWP is not a fixed-interest or guaranteed-income product. The remaining investment continues to be affected by the performance of the underlying mutual fund, while every withdrawal reduces the units you hold.
Ready to set up a Systematic Withdrawal Plan?
Open Your Shoonya Account →Systematic Withdrawal Plan : FAQs
What is SWP?
SWP stands for Systematic Withdrawal Plan. It allows an investor to withdraw a specified amount from a mutual fund investment at predetermined intervals.
What is SWP in mutual fund?
SWP in a mutual fund is a facility through which a specified amount or number of units is periodically redeemed from an investor’s existing mutual fund holding.
Is SWP a good investment?
SWP itself is not an investment product. It is a withdrawal facility available on eligible mutual fund investments.
Does SWP have an interest rate?
No. There is no fixed SWP interest rate. Returns depend on the underlying mutual fund, while SWP payments are made by redeeming units.
Can I stop an SWP?
Generally, yes. Investors can request discontinuation of an SWP, subject to the AMC or scheme’s applicable terms and notice requirements.
Can I change my SWP amount?
This depends on the mutual fund scheme’s terms. You may need to modify or cancel the existing instruction and submit a fresh SWP request.
Is SWP taxable in India?
SWP instalments involve redemption of mutual fund units, so any capital gain arising from the units redeemed can be taxable according to the applicable mutual fund taxation rules.
What is the difference between SIP and SWP?
SIP regularly invests money into a mutual fund, whereas SWP regularly withdraws money from an existing mutual fund investment.
Can I use SIP and SWP together?
SIP and SWP serve opposite purposes and may be used at different stages of an investment journey. SIP helps invest periodically, while SWP provides periodic withdrawals from an accumulated mutual fund holding.
How long can an SWP continue?
It depends on the SWP instruction, scheme rules and availability of sufficient units in the mutual fund account. An SWP may stop when the specified period ends or the available investment is exhausted.


Explore Our Offerings

Stocks
Trade equities across NSE and BSE with zero delivery charges. Invest, hold or sell with a seamless experience.


Future & Options
Execute complex strategies with simple tools and real-time data.

IPOs
Apply to the latest IPOs in just a few taps. Stay updated and capture opportunities as they open.